


Welcome to the seminar. Before we dive in, a few logistical items:
If you haven’t yet, please introduce yourself in the introduction thread
I posted a Reading List post which I will update ahead of when you need to get each book/resource. Keep an eye on it and order these in advance so that they don’t become a bottleneck
It’s not too late: please share this post with friends or colleagues who you think would enjoy joining us. More serious, engaged students = better learning environment for everyone. Plus, you are less likely to quit if you have a buddy doing this with you
Please don’t take engaging with other people’s answers in the comments section as optional. It will enhance both your learning and everyone else’s
I am going to make a small change, and rather than automatically send out one assignment per week, I will have some assignments span 2 weeks. The reason is to combine rigor with a reasonable amount of time for busy folks like you to finish the assignments. The default is still one week, so unless I say otherwise everything should be done by early Friday morning the following week
As I wrote in the introduction, we are going to study the investing greats and put their styles and investment processes through our understand, apply, and customize framework. The goal is to help you develop the best investing style and process for you.
Before we begin with this week’s reading, let’s dive a bit deeper into what makes an investing style. As you study the masters, it would be helpful if you could do more than just say, “Gee, I like how he does that,” and get more specific about what you might want to incorporate into your own approach and what you would rather leave out. The framework I like to use for this is dimensions of an investing style.
Think of a dimension of a style the way you would think of an x- or y-axis in geometry. Each dimension is independent of the others. There are many dimensions, and far more possible investing styles based on the various combinations of “values” along each dimension.
There are many valid ways to combine how a style is positioned on each dimension. However, not every combination is equally rational. Let me explain with an example.
Let’s take two dimensions, Diversification and Depth of Research. Of course, dimensions have a continuum of values, but for the sake of simplicity let’s assume that each of these can take one of two values:
Diversification: Very Diversified or Highly Concentrated
Depth of Research: Shallow or Deep
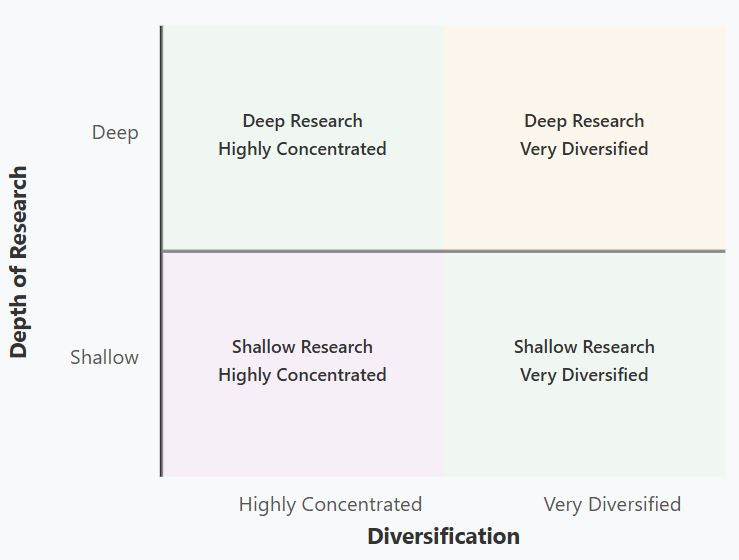
Let’s think through each of the four combinations:
Deep Research, Highly Concentrated: Makes perfect sense — if you are going to concentrate, you better know your investments well.
Shallow Research, Very Diversified: Also very rational — if you know each investment just superficially (e.g. a valuation statistic only), you best diversify broadly.
Deep Research, Very Diversified: On the surface this might not make sense, but it could. For example, imagine a large firm with an army of analysts. Each analyst could have a lot of depth on a small number of investments and the portfolio manager could construct a diversified portfolio out of their ideas.
Shallow Research, Highly Concentrated: This one makes no sense and would be a recipe for investing disaster.
The point is that while there are many valid ways to combine positioning along the different dimensions, there are also invalid combinations. Many things go, but not everything does.
Question 0: Come up with as many other dimensions of an investing style as you can and provide a scale for each of those dimensions (e.g. Diversification [high to low]). Hint: The highest number of dimensions that I’ve received over the years in response to this question was 20+, so don’t give up too soon.
Now let’s move on to our reading for this week: Benjamin Graham’s Security Analysis, Part 1. Before we get to the questions, a few words about why I am starting our journey here. After all, several professional investor friends have disagreed with this choice.
Here is the thing: investing is hard, and it takes hard work to become good at it. Many will not want to put in the effort to study Security Analysis. I understand. It’s not beach reading, that’s for sure.
It would be much easier to start with, say, Graham’s Intelligent Investor, easily digest the concepts and feel good about ourselves. That would, however, deprive the serious student of the real opportunity to learn, and that’s who the seminar is designed to benefit the most. After all, Graham intended The Intelligent Investor for the casual audience and Security Analysis for the serious professional.
You might be thinking, “But isn’t Security Analysis outdated? Does it still apply when so much about the investing world has changed since Graham wrote it? Aren’t there whole industries that weren’t around back then, new types of businesses and technology, and so on?”
And as I write this in the fall of 2026, years into a momentum-driven bull market, some of you are probably wondering if “classical” value investing is still relevant at all.
I don’t blame you. Yes, things are different. We will discuss those differences since it’s core to how we would want to apply Graham’s ideas today. Some of you might decide that much, or all of Graham’s approach doesn’t fit how you want to invest. That’s fine. First, let’s understand it, master the fundamentals, and then customize in a way best for each one of us in the current era.
Question 1: When did Graham write the first edition of Security Analysis and how did the environment during which he was operating and writing influence his work?
Question 2: What’s Graham’s investment philosophy? Why does he think that’s best?
Question 3: Which parts of his approach do you think you want to imitate? Which ones do you think you would rather not? Why? (we will revisit this at the end of the book)
Question 4: What’s the difference between an investment and a speculation? Why did Graham choose the words that he did to define it, and what are the implications of his choices for investing?
Now it’s your turn:
Submit your answers in the comments below this article with all your answers in a single comment. I will engage with some of the answers each week and highlight some of the ones I find most insightful in next week’s seminar assignment article.
Engage with the answers of some of your fellow seminar members in the comments below. Remember: the goal is to learn together. Be kind, be respectful and try to add to our learning as a community.
Feel free to ask any questions about the reading in your comment.
Until next week,
Gary
About the author
Gary Mishuris, CFA is the Managing Partner and Chief Investment Officer of Silver Ring Value Partners, an investment firm that seeks to apply its intrinsic value approach to safely compound capital over the long-term. He also teaches the Value Investing Seminar at the F.W. Olin Graduate School of Business.
I'm going to start with Question 0 on Investment Style as its own separate post. The more I think about dimensions and investment style, it comes down to either some type of feature of the company that one is investing in (for example, market capitalization, dividend growth, cash level, insider ownership dimension, etc.) or one's temperament or mandate or preference per individual/institutional investors (e.g., holding period dimension, tax efficiency dimension).
Investment Style
⦁ 1) Holding period dimension (with the dimension being from short to long - i.e., a couple months - short-term gains realized versus long-term gains (due to holding securities for more than 1 year + holding securities for very long periods, e.g. 10 years or more)
⦁ 2) Tax efficiency dimension (high - low) - tax efficient (infrequent trading, with a view toward minimizing taxes) versus non-tax efficient (frequent trading/high turnover to realize capital gains)
⦁ 3) Dividend/dividend growth style - capital allocation by company that favors a dividend payout. Dimension of high dividend declaration by board of directors for a company to none - i.e., no dividend/no payout to shareholders.
⦁ 4) Share buyback companies (companies that eat themselves) versus no share buyback companies - Buyback dimension (high to low/none)
⦁ 5) Microcap/Small cap (market capitalization - e.g., OTC markets) versus Blue chip/S&P 500 (very large companies) - Market Capitalization dimension (small to mega-cap)
⦁ 6) Thinly traded companies (could be large companies on foreign exchanges) versus highly liquid companies (very established mega caps) on stock market exchanges - Liquidity dimension (low to high)
⦁ 7) Domestic companies (e.g., headquartered in country) versus international companies (or companies that sell a lot to international customers) - Geographical Domestic/Foreign dimension
⦁ 8) News/media prominence (companies in the news/making headlines) versus undiscovered companies (companies that do not make headlines/obscure/misunderstood/niche) - Media coverage dimension (high to low)
⦁ 9) Debt (companies that have a lot of debt e.g. utilities, real estate) versus no debt - Debt dimension (high to low/none)
⦁ 10) Cash rich companies (cash/investments on the balance sheet) versus no cash/financing via debt/selling shares to fund its operations - Cash Levels dimension (high to low/none)
⦁ 11) Active (stock picker/securities selector) versus passive investor (e.g., dollar cost average into index funds) - Active-Passive Investor dimension
⦁ 12) Defensive investor (investing to protect principal from being eroded by inflation/preserve principal) versus enterprising investor (active securities selector) - Investment Portfolio Aggressiveness dimension (defensive to enterprising)
⦁ 13) Fundamental Investor versus Story Stock investor (likely due to no earnings/losses for young companies) - Investment Research dimension
⦁ 14) High technology level companies (companies influenced by technological trends, technology sector companies) versus low technology companies (companies that are relatively insulated from technological trends - e.g., tobacco companies) - Technological Trend dimension (high to low)
⦁ 15) Local companies (based near the area of the investor's interest) versus global companies (based internationally, multiple headquarters, etc.) - Investment Locale dimension
⦁ 16) Introspective investment style (reading annual reports, proxies, no conversations with the company management's team - i.e., being an armchair investor) versus extrovert investment style (talking to suppliers, customers, employees, flying to meetings, etc.) - Research Process Orientation Dimension (introspection to extraversion)
⦁ 17) High insider level ownership versus low/no insider level ownership - Insider Ownership dimension (high to low)
⦁ 18) Low CEO pay (relative to company's market cap) versus high CEO pay (e.g., a high CEO to median employee pay ratio) - CEO Compensation dimension (high to low)
⦁ 19) Companies with significant moats (e.g, patents, scale, location) versus non-moat/commodity companies - Moat dimension (high to low)
⦁ 20) High profit margin companies (e.g., hyperscalers, drug companies) versus very low profit margins (e.g., healthcare suppliers, mining companies) - Profit Margin dimension (high to low)
⦁ 21) Dimension of government regulation - companies with a lot of government regulation (e.g., healthcare, banks, utilities) versus companies that do not have a high level of government regulation (e.g., retail, one product company) - Business Regulation Level (high to low)
⦁ 22) High CEO prominence/family-run companies versus low CEO prominence/outsider led companies (i.e., governance by non-family) - Family business/governance dimension (high to low)
⦁ 23) Acquirers (companies that grow via acquisition) versus organic growth companies (no M&A activity) - Growth generation dimension (acquirer to organic growth)
⦁ 24) Financially sensitive companies (companies very sensitive to interest rate risk - e.g., banks, insurers, real estate) versus non-financial companies - Interest Rate sensitivity dimension (high to low)
⦁ 25) Startup investing (very young companies) versus investing in mature/established companies - Company Maturity Level dimension (early to mature)
⦁ 26) Business cycle investing - investing in high growth companies during the growth phase of the business cycle versus investing in companies which are at a trough - Business Cycle dimension (trough to growth)
⦁ 27) Companies with high levels of employee ownership (e.g., stock ownership plans) versus low or no employee ownership - Employee Ownership dimension (high to low)
⦁ 28) Companies which have very high numbers of shareowners (broad shareholder ownership) versus companies that are highly concentrated (held by a small number of shareholders - undiscovered companies) - Shareholder Ownership dimension (high to low)
⦁ 29) Rapidly growing companies (e.g., in terms of sales/revenue) versus slow growth companies or even industries in decline (e.g. tobacco) - Corporate Growth dimension (fast to slow)
⦁ 30) Companies hitting record stock price highs versus companies that are hitting record lows - Market Sentiment dimension (high to low)
It's almost idiosyncratic, as one can invest on a myriad number of dimensions. In weighing each investment with investment style, I'm reminded of the French philosopher and essayist Michel de Montaigne: "There never were, in the world, two opinions alike, no more than two hairs, or two grains; the most universal quality is diversity."
Hi
Question 1) First edition of security analysis has been published in 1934. Graham and Dodd worked on the book from 1930 to 1934. The background in which the book has been written is that of collapse of wall street and the subsequent great depression. More important, in my opinion, is that the ideas that lie inside were conceived before the 1929 in an era of exagerated optimism. It can be said that the work of Graham and Dodd is a kind of anthidote manifest against the irrationality and, looking deeper, a translation in finance of the Hegel philosophy where he forecasts the human behaviour as an endless cycle in which every behaviour is brought to paroxysm and then fell back.
Question 2) Graham thinks that the investor must go trough an hard and scroupolous work of analysis. The main goal of analysis is to exclude the stock or bond that does not have the "margin of safety" . So the main work of the investor is to exclude, is to have a safeguard against what can reasonably happen to the business he is investing in. In short words the investment philosophy is avoid to lose money.
Question 3) I would like to imitate the discipline in the selection process. At the same time I am worringly consider not to have the sufficient strenght.
Question 4) an investiment is the one that after a deep analysis promise the safeguard of capital and a satisfying yield. The operations that do not satisfy these requirements are speculations. In the sentence the main concepts of Graham phylosophy are condensated. "Analysis", "Safeguard of capital", "yield". So the focus of the investor (NOT the speculator) has to be put in these 3 axes. Hence the investor must go through the hard work of analysis in order to exclude the "not safe" opportunity of investment (and the safeguard of capital) and choose those that will preasumably guarantee a reasonable yield. The implication is that the investor mist be like a blind who relies on his stick (the analysis) and ruthleslessy focus on the "sound oportunity"